Take on your biggest challenges
Onboarding KYC & AML
Customers are verified in minutes from their phone, and your compliance teams hold a complete, traceable file.
Open accounts remotely without giving up compliance
Know-your-customer (KYC), know-your-business (KYB) and anti-money-laundering obligations weigh on account opening times. We put in place an identity verification and risk screening chain that fits into your digital journeys, shortening those times without weakening your compliance.
We support banks, insurers and microfinance institutions in modernising their compliance and customer risk management frameworks.
Remote onboarding
ID document, selfie and supporting documents are collected and checked from a mobile or a browser, with no branch visit.
Automated regulatory checks
Sanctions lists, politically exposed persons and risk signals are screened at onboarding, then monitored over time.
A complete audit trail
Every decision, document and check is time-stamped and retained, ready to present to the regulator.
Sectors covered
Industries served
01
Remote identity verification
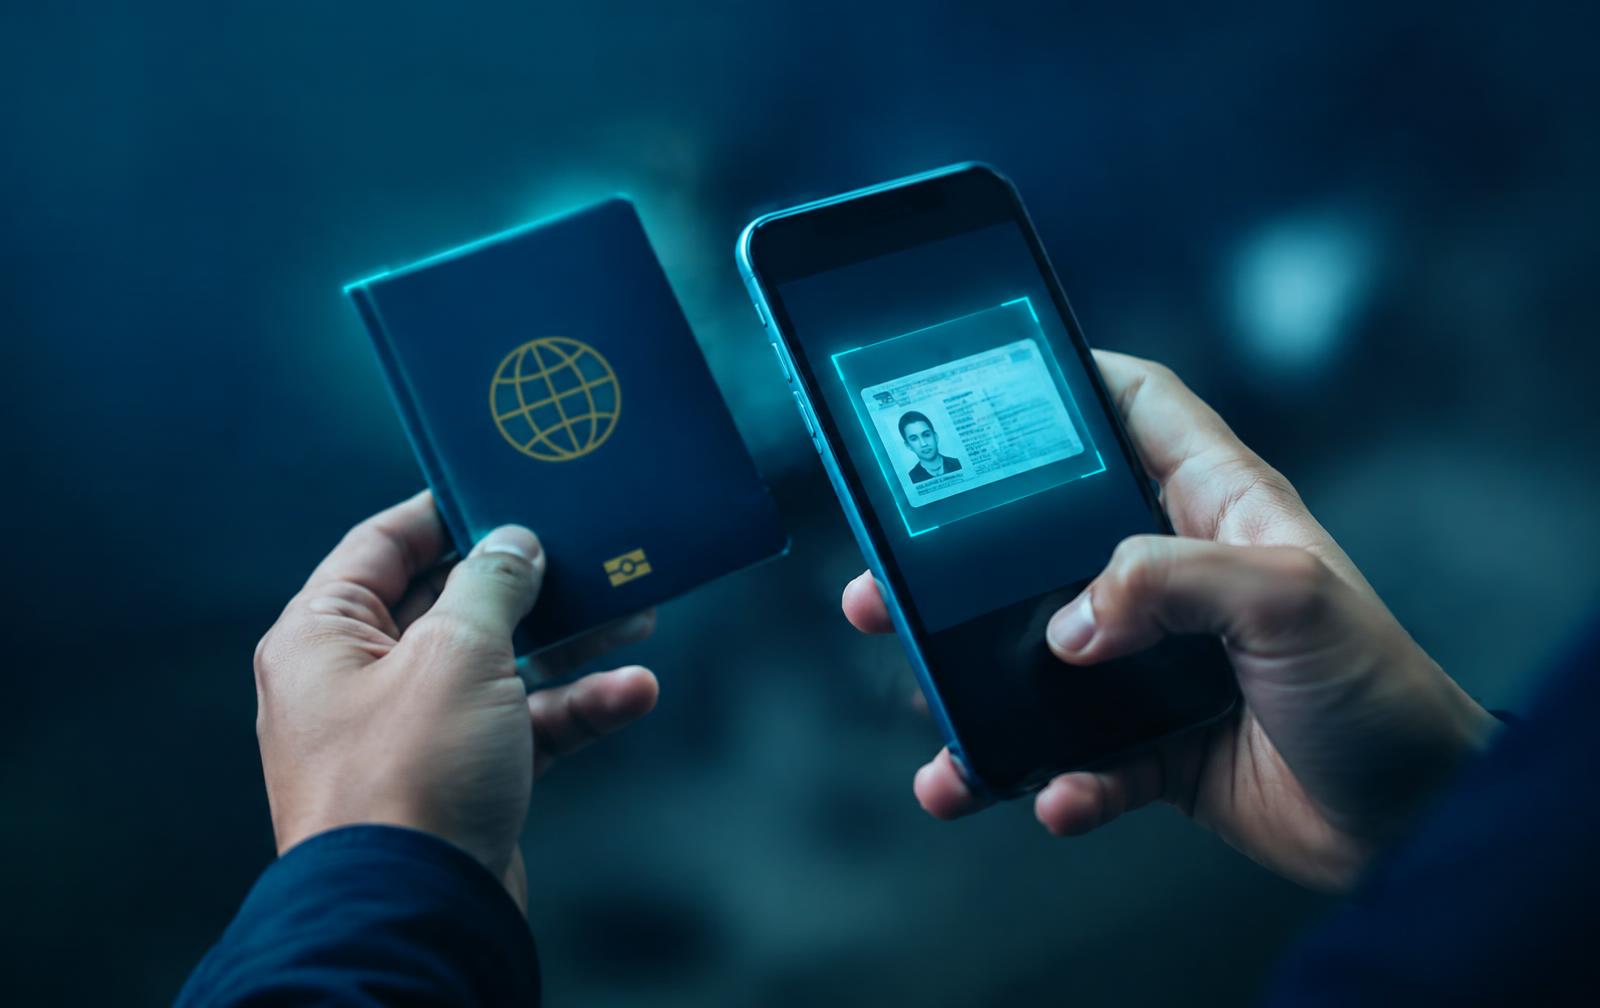
The verification journey sits inside your app or website: the customer photographs their ID document, passes a liveness check and receives an answer within minutes.
In detail
- Automated document reading: extraction of ID data and consistency checks.
- Biometric check: face comparison against the document and detection of photo or replayed-video fraud.
- Address and supporting documents: bills, certificates or statements checked against your internal rules.
- Business verification (KYB): see the dedicated section below.
- Mobile and web journeys: translated interface, designed for limited connectivity and entry-level devices.
02
KYB: verifying business customers
When the customer is a business, you need to know the company itself, not just the person opening the account: who owns it, who runs it and who can act on its behalf.
In detail
- Company identification: checks on registration details, articles of association and official documents.
- Ownership structure: identification of shareholders and beneficial owners.
- Directors and representatives: identity verification of each director and signatory, using the same journey as KYC.
- Risk checks: screening of the company, its directors and its beneficial owners against sanctions lists, politically exposed persons and adverse media.
- Ongoing monitoring: file review when the company changes directors, shareholders or situation.
03
Compliance and risk monitoring
Onboarding checks are only one step: risk evolves throughout the relationship. We equip your teams to follow it.
In detail
Regulatory screening
- Screening against sanctions and embargo lists.
- Detection of politically exposed persons and adverse media.
- Customer risk scoring on your own criteria, with differentiated levels of due diligence.
- Ongoing monitoring: files are automatically re-examined when a new signal appears.
Run by your compliance teams
- Case handling workspace: approve, request additional documents or decline with a reason.
- Automatic decision rules for simple cases, human review for sensitive ones.
- Full traceability of decisions and retention of evidence.
- Monitoring indicators: volumes, acceptance rates, processing times and rejection reasons.
04
Combating money laundering and terrorist financing
Beyond identifying the customer, anti-money laundering requires monitoring their transactions over time and reacting to unusual behaviour. We equip your teams to detect, analyse and document these situations.
In detail
Transaction monitoring
- Analysis of transactions using scenarios tailored to your business: unusual amounts, structuring, abnormal frequency.
- Screening of flows to or from high-risk countries and counterparties.
- Alerts prioritised according to the customer's risk level.
Investigation and reporting
- Alert investigation by analysts, with the customer's full history.
- Preparation of the suspicious transaction report for the financial intelligence unit.
- Retention of evidence and traceability of every decision.
Risk-based due diligence
- Enhanced due diligence for high-risk customers and politically exposed persons.
- Regular review of customer files according to their risk level.
- Monitoring reports for compliance management.
05
Integration and go-live
In detail
- Regulatory framing: translating your obligations and internal policy into screening rules.
- Technical integration: connection to your app, core systems and case management tools.
- Test environment: validation of journeys and edge cases before public launch.
- Training for compliance and customer service teams, then support after go-live.
Not sure which offer fits? Talk directly with an Arès expert.
Describe your needA certified platform aligned with international standards
Solutions, expertise and support